Moving From a House to a Condo: What Changes in Space, Storage and Services
The moving companies cover the boxes. This is the rest of it: what you give up, what the association takes over, and what a lender checks about the building before it checks you.
By Moe Hannon, Realtor · Ellyn & Main at KW Premiere Properties, Elmhurst IL · Updated September 2026
- The square footage number will mislead you. A condo is often measured differently from a house, so the same figure can feel smaller once you are standing in it.
- Storage decides more of these moves than space does. A basement, an attic, a garage and a shed are four storage rooms most condos do not have.
- The association takes over the outside, not the inside. Roof, exterior, snow and landscaping usually move off your list. Appliances, fixtures and finishes stay on it.
- Your lender reviews the building, not only you. A condo loan depends on the association's finances and paperwork as well as your own file.
- Sorting starts before the search. Knowing what you are keeping is what makes the right unit recognizable when it comes up.
Moving from a house to a condo is a bigger change than the floor plan suggests. Most of what you will read about it comes from moving companies, and it is good advice about boxes and packing. What it skips is the part that happens before the truck: what you are giving up, what the association will and will not take off your hands, and what a lender looks at in a condo building before it approves your loan.
That part is the listing agent's side of the move, which this guide covers for anyone right-sizing out of a family house in Elmhurst, Glen Ellyn and Wheaton. Here is what changes, in the order it tends to surprise people.
Square footage is not measured the same way
Start with the number on the listing, because it causes the first disappointment. A single-family house is commonly measured from the outside of its exterior walls. A condo unit is often measured from the inside, or described using a figure from the building's own documents, and listings are not consistent about which one they use. The two numbers are not always answering the same question.
So a condo listed at a similar size to your house can feel smaller once you walk it, and nothing about that is a mistake on the listing. It is the measurement. The practical fix is simple: stop comparing totals and start comparing rooms. Walk your house with a tape measure and write down the sizes of the rooms you use every day, the ones where the furniture you are keeping will go. Then compare those rooms, not the total.
A total also hides layout. A house spreads its space across floors, with stairs and hallways taking a share, while a single-floor unit puts all of it on one level. That can make a smaller unit feel bigger, or make one open room feel like too little separation.
The same mismatch shows up on every kind of listing, not only condos, and why square footage differs on listings covers who measured each number and how.
If the condo you want comes up before your house sells, how to line up the two closings shows what each order costs you in time and risk.
Storage is the thing that ends up deciding it
A basement, an attic, a garage and a shed are four storage rooms. A condo usually gives you a closet or two, sometimes an assigned storage locker somewhere in the building, and a parking space. That is the real downsizing, and it is bigger than the drop in bedrooms.
This is why the sorting has to start before the search, not after the offer. If you do not know what you are keeping, you cannot tell whether a unit works. It is easy to fall for a view and only later realize there is nowhere for the holiday decorations, the tools or the extra chairs. Deciding what comes with you first turns a vague feeling into a list, and a list is something you can hold up against a floor plan.
Two questions worth asking about any building. Is there a storage locker assigned to this unit, and does it come with the unit or is it rented separately? And for parking, is the space deeded, assigned or first-come? Those answers live in the building's documents, and they matter more than most finishes.
What changes, house to condo
| Area | What you had | What you usually get | What people underestimate |
|---|---|---|---|
| Space | Rooms spread over two or three floors | Everything on one level, often measured differently | How the same number can feel smaller in person |
| Storage | Basement, attic, garage, shed | A closet or two, maybe a building locker | How much has to be decided before the move |
| Outdoor space | A yard you control | A balcony, a patio or shared grounds | That shared grounds come with rules about their use |
| Exterior upkeep | Yours: roof, gutters, siding, snow | Usually the association's | That the board decides when and how it gets done |
| Interior upkeep | Yours | Still yours: appliances, fixtures, finishes | That almost everything inside the unit stays your job |
| Utilities | All billed to you | Some may be covered by assessments | Which ones, and that it varies building to building |
| Insurance | One homeowner's policy on the whole structure | The building's master policy plus your own unit policy | That the master policy does not cover everything inside your unit |
| Parking | A driveway and a garage | Deeded, assigned or open parking | How guest parking works |
| Rules | The village's | The village's plus the association's | Rules on pets, renovations, rentals and move-in times |
Nothing in that table is a reason not to move. It is a list of what to check, so none of it arrives as a surprise after closing.
What does the association take over, and what does it not?
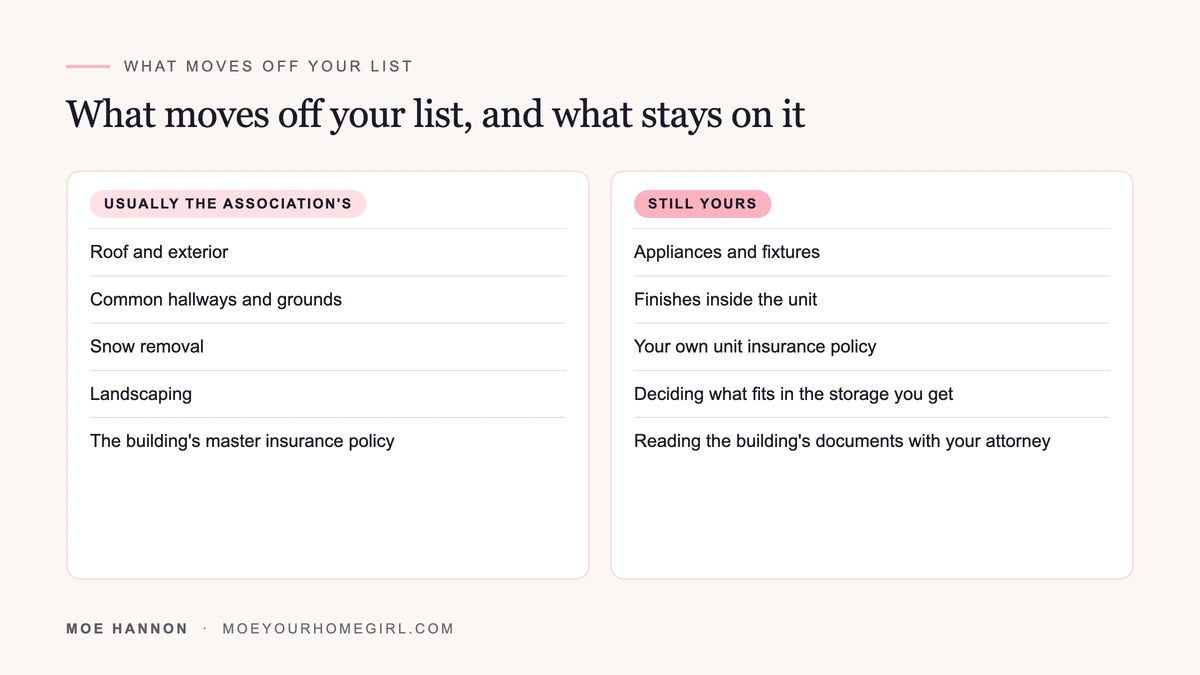
The appeal of a condo for a lot of people leaving a house is simple: no more ladders, no more snow blower, no more calling someone about the gutters. That is mostly true. In most buildings the association handles the exterior, the roof, the common hallways, snow removal and landscaping, and it pays for that work out of the assessments every owner contributes.
What changes is who decides. In a house, you choose when the roof gets done and who does it. In a condo, the board decides, on the board's schedule, and the cost is shared across the building. Some people find that a relief and some find it hard after decades of making every call. Know which one you are before you buy.
And the inside is still yours. Appliances, fixtures, finishes and generally everything within your unit are your responsibility, and so is insuring them. The building's master policy covers the building, and your own unit policy covers the rest. The exact split is written into the condominium documents, which is one more reason those documents matter.
The building's paperwork is part of the purchase
Illinois gives a condo buyer a right that a house buyer never needs. Under Section 22.1 of the Illinois Condominium Property Act, an owner reselling a unit has to obtain a specific set of documents from the board and make them available to the buyer on request. The list includes the declaration, bylaws and rules, a statement of any unpaid assessments on the unit, any capital expenditures the association expects in the current year or the next two, the status of the reserve fund, the association's financial statement, any pending lawsuits, and the insurance the association carries.
That list is the building's report card. Your attorney reads it with you during attorney review, and it is where you find out about a planned roof project, a lawsuit or a thin reserve before you are committed. I make sure the request goes in early so the documents arrive while there is still time to act on them. Reading them and advising you on what they mean is your attorney's job, not mine, and I will say so plainly.
Will your lender review the building as well as you?
This is the fact most people moving from a house have never had to think about. When you finance a house, the lender underwrites you and appraises the property. When you finance a condo, the lender also looks at the building. Fannie Mae's Selling Guide puts it directly: before delivering a loan on a unit in a condo project, the lender must determine that the project meets its eligibility requirements, and it treats the project's risk as separate from the borrower's own credit.
In practice, the association's budget, how many owners are behind on assessments, pending litigation and the building's insurance can all affect whether a particular loan is available for a particular unit. FHA loans have their own approval list for condo projects, which HUD publishes as a searchable list. None of this is a reason to avoid condos. It is a reason to give your lender the name of the specific building early, before you are attached to a unit, and let them tell you what they will need.
Two closings, lined up
Most people moving from a house to a condo are selling one and buying the other, and those are two transactions that have to meet in the middle. Whether you sell first, buy first, or line both closings up on the same day depends on your finances and on how you feel about a short-term rental or a double move. That decision deserves its own conversation, and it is the first one I have with anyone working with me as a downsizing realtor in Elmhurst.
The one point that belongs here: in any single building, the supply of units is thin. The unit that fits, in the building you want, may not come up often, and when it does it will not wait for your house to sell. Knowing your timing in advance is what lets you move when it does. If the house you are leaving sits on an older lot, the block-level signs that a house is a teardown show how a builder may read it before you list.
And if the building is the one you want, the condo reserve study shows how it plans to pay for big repairs, so read it before you write the offer.
I will not tell you a building is a good investment. I can tell you what comparable units have sold for, what the documents say, and what your lender is likely to ask for. Whether a building's finances are sound is for your attorney to read and for you to decide. And a smaller home is not automatically a cheaper one. Assessments, a new tax bill and the cost of the move all belong in the math, and I will say that before you are under contract, not after.
Moving from a house to a condo goes best when you decide what you are keeping before you start looking, ask about storage and parking before you fall for a view, and put the building's paperwork and your lender's review on the calendar early. More plain-English help for the moments that force a move is in the guides.
Sources: 765 ILCS 605, Illinois Condominium Property Act · Fannie Mae Selling Guide, B4-2.1-01 General Information on Project Standards · HUD, FHA Approved Condominiums. Opened and read on 2026-09-23.
Moving from a house to something smaller?
Tell me about the house you are leaving and what you want next. I will lay out the order of the move before anything goes on the market.
Straight answers, no hedging.
Why does a condo feel smaller than its square footage?
Because condo units are often measured differently from houses, commonly from the inside, while a house is usually measured from the outside of its exterior walls. Layout plays a part too. Compare the sizes of the rooms you will use every day rather than the total, and measure the furniture you plan to keep.
What does a condo association usually take care of?
Generally the exterior, the roof, common areas, snow removal and landscaping, paid for from the assessments owners contribute. The inside of your unit, including appliances, fixtures and finishes, usually stays your responsibility. The exact split is written into the building's condominium documents, so read them with your attorney.
Can the condo building affect my mortgage?
Yes. Lenders review the condo project as well as the borrower, including the association's finances, insurance and any litigation, and FHA keeps its own list of approved condo projects. Give your lender the name of the building early so you know what they need before you make an offer.
What documents should I see before buying a condo in Illinois?
The Illinois Condominium Property Act requires an owner reselling a unit to make a set of association documents available to the buyer on request. They include the declaration, bylaws and rules, the unit's assessment account, expected capital expenditures, the reserve fund status, the financial statement, pending lawsuits and insurance coverage. Your attorney reviews them with you, usually during attorney review.
About the agent
I'm Maureen - but everyone calls me Moe. I have been selling real estate since 2019 and I work out of the Ellyn & Main team at KW Premiere Properties, 100 N Addison Ave in Elmhurst. I hold the Seller Representative Specialist and C2EX designations along with a Luxury Homes certification, and I am a member of KW Luxury. At least $250 of every commission check goes to ShowerUp Chicago and the YMCA of Elmhurst, where I sit on the board. If you are thinking about moving from a house to something smaller and want the order of it laid out plainly, call me at 630-890-5430.
This is a realtor's guide, not legal advice.